A one-time loan settlement can provide relief when a borrower is genuinely unable to repay the entire outstanding amount. The lender agrees to accept a lower negotiated amount and closes its recovery for the remaining dues according to the settlement terms.
However, a loan that has been “settled” is not the same as a loan that has been fully “closed.” This difference becomes important when the borrower later applies for a home loan, car loan, personal loan or credit card.
A settlement may resolve the immediate debt problem, but the way the account is reported to CIBIL can continue to influence future lending decisions.
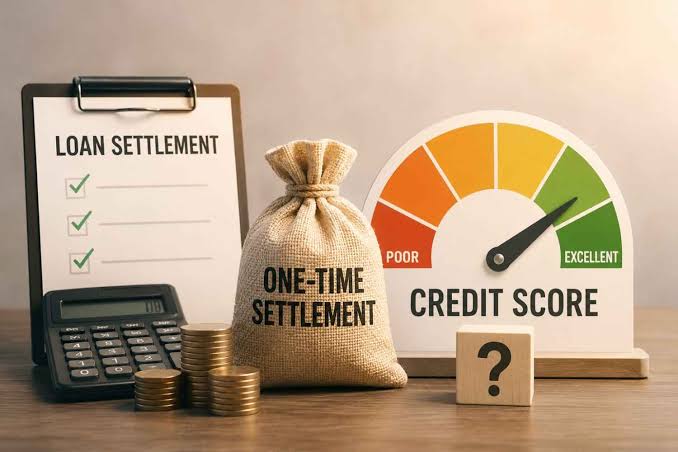
What Does “Settled” Mean in a CIBIL Report?
Suppose you owe a lender ₹3 lakh but are unable to repay the full amount.
After negotiations, the lender agrees to accept ₹2 lakh as a one-time settlement. You pay ₹2 lakh and the lender agrees not to pursue the remaining ₹1 lakh under the agreed settlement.
Because the complete contractual amount was not paid, the lender may report the account to CIBIL as:
Settled
If the entire amount due had been repaid according to the lender’s requirements, the account would normally be reported as:
Closed
CIBIL itself explains that a “settled” status indicates that the borrower and lender agreed to payment of an amount lower than the complete amount payable.
Why Is “Settled” Considered Negative?
From the lender’s perspective, a settlement means the previous lender did not recover the complete amount it was contractually entitled to receive.
A future lender looking at the CIBIL report may therefore ask:
- Why was the complete loan not repaid?
- Was there a prolonged period of default?
- Could the borrower face repayment problems again?
- How recently did the settlement happen?
- Has credit behaviour improved since then?
For this reason, CIBIL states that lenders generally view a “settled” account unfavourably because it indicates that the borrower did not completely meet a previous repayment obligation.
Does One-Time Settlement Reduce the CIBIL Score?
The impact should not be viewed only in terms of the word “settled.”
Before a loan normally reaches the settlement stage, there may already have been:
- missed EMIs;
- overdue amounts;
- increasing Days Past Due;
- collection activity; or
- prolonged repayment irregularities.
These repayment events can damage the borrower’s credit profile.
The subsequent “settled” status then provides future lenders with additional information showing that the loan was ultimately resolved for less than the complete contractual amount.
Therefore, even where the numerical CIBIL Score later improves, the account information in the credit report can still influence a lender’s decision.
Can You Get Another Loan After a Settlement?
Yes. A past settlement does not create a permanent legal ban on borrowing.
However, obtaining new credit may become more difficult, particularly shortly after the settlement.
A future lender may:
- reject the application;
- sanction a smaller amount;
- offer a higher interest rate;
- require additional security;
- ask for a stronger co-applicant;
- seek an explanation about the previous settlement; or
- conduct a more detailed credit assessment.
CIBIL itself gives an example of a borrower whose education-loan application was rejected because an earlier personal loan was reported as “settled.”
The actual decision remains with the lender.
Home Loans Can Be More Sensitive to Past Settlements
A home loan involves a large amount and often continues for 15 to 30 years.
Banks therefore examine the borrower’s complete credit history, not simply the current CIBIL Score.
A borrower may have rebuilt the score to 750 or even higher but still have a previous settled account visible in the report. A lender can take that history into consideration while assessing the application.
The age of the settlement, amount involved, reason for default, subsequent repayment record, current income and overall financial position can all influence the final decision.
Can a “Settled” Account Be Changed to “Closed”?
In some situations, yes.
CIBIL explains a process in which a borrower who previously settled a loan later paid the remaining outstanding amount to the lender.
After receiving the balance payment, the lender issued a No Objection Certificate. Once the lender confirmed the updated position to CIBIL, the account status was changed from “settled” to “closed.”
Therefore, if you have previously settled a loan and now want to improve your credit profile, contact the original lender.
Ask whether it will accept the remaining amount necessary to treat the loan as fully paid.
How To Change Settled Status to Closed
The process generally starts with the lender, not CIBIL.
1. Contact the Original Lender
Ask the lender for the amount required to clear the remaining liability associated with the settled account.
Do not calculate the amount yourself because the lender must determine what it requires for updating the account.
2. Obtain the Amount in Writing
Request written confirmation of:
- loan account number;
- amount payable;
- conditions for full closure; and
- whether the lender will report the account as closed after receiving payment.
This helps avoid another dispute later.
3. Pay the Required Amount
Make the payment directly through an authorised channel and preserve proof of payment.
4. Obtain a No-Dues or No Objection Certificate
After payment, request appropriate written confirmation that the account has been fully cleared.
5. Allow the Lender To Update CIBIL
Credit-report information comes from lenders.
CIBIL cannot independently change a lender-reported “settled” account to “closed” simply because the borrower requests it. The concerned lender must confirm the corrected information.
6. Check Your Updated CIBIL Report
After the lender’s reporting cycle, check whether the status has changed.
If the lender confirms that it has updated the account but the report remains incorrect, you can raise a CIBIL dispute.
Will CIBIL Delete the Entire Settlement History After Full Payment?
Do not expect the complete account to disappear simply because it has been paid.
Closed loans can continue to appear in a CIBIL Report because they form part of the borrower’s credit history. CIBIL specifically states that closed accounts continue to reflect in the report as historical information.
The important improvement is that the current account status may change from “settled” to “closed” after the lender confirms that its requirements for full payment have been satisfied.
However, historical repayment information from the period before closure may continue to form part of the credit record.
Does Paying the Remaining Amount Immediately Restore Your Score?
Not necessarily.
Changing an account from settled to closed is an important improvement, but credit rebuilding takes time.
The earlier late payments do not suddenly become timely payments simply because the remaining loan amount has now been cleared.
Future improvement generally comes from maintaining clean credit behaviour such as:
- paying every EMI on time;
- paying credit-card bills on time;
- keeping card utilisation under control;
- avoiding unnecessary loan applications;
- maintaining manageable debt; and
- regularly checking the credit report for errors.
CIBIL reports contain repayment history and account information that lenders can use while evaluating a borrower.
Should You Accept a One-Time Settlement?
A genuine settlement can be useful when severe financial difficulty makes full repayment impossible and the alternative is continued default.
However, it should not normally be chosen simply because it allows you to repay less money.
If you have the ability to repay the complete outstanding amount, full repayment and normal closure generally leave a much healthier credit record.
Before accepting a settlement, ask the lender exactly how the account will be reported to credit bureaus.
Do not assume that the words “full and final settlement” automatically mean the CIBIL status will show “closed.”
These are different concepts.
What If the Lender Incorrectly Shows “Settled”?
If you actually repaid the complete amount but the lender has reported the account as settled, first contact the lender with proof such as:
- payment receipts;
- loan statements;
- closure letter;
- No-Dues Certificate; and
- bank statements showing payment.
Ask the lender to correct its reporting.
If the lender has already corrected its records but the information is still wrong in your CIBIL Report, raise a dispute with CIBIL.
CIBIL cannot make the correction by itself. It must receive confirmation from the institution that supplied the information.
How To Rebuild Your CIBIL History After Settlement
Once the settlement issue has been resolved, concentrate on building a clean recent repayment history.
If possible, first try to convert the settled account to closed by paying any remaining amount required by the lender.
Then maintain all existing loans and credit cards without delay.
Avoid repeatedly applying for loans merely to see whether you now qualify. Multiple applications create additional credit enquiries and can make a borrower already recovering from previous financial difficulty appear credit-hungry.
Over time, a consistent record of responsible repayment can make the old problem less important relative to your stronger recent credit behaviour.
FAQs
Q1. How long does a settled loan affect future loan eligibility?
There is no single period after which every lender must ignore a settlement. The account can remain part of your credit history, while individual lenders decide how much importance to give it based on its age, amount, circumstances and your subsequent repayment behaviour.
Q2. Can I get a home loan after a one-time settlement?
Yes, but approval may be harder, particularly if the settlement is recent. A stronger current CIBIL Score, stable income, good repayment behaviour, lower debt and conversion of the old account from settled to closed can strengthen the application.
Q3. Will paying the remaining settlement amount remove the old account from CIBIL?
Usually, the objective is not to delete the account. After the lender accepts the required balance and reports the update, the status may be changed from “settled” to “closed.” The account can still remain visible as part of your credit history.
Q4. Is “closed” better than “settled” in a CIBIL report?
Yes. “Closed” normally indicates that the loan obligation has been fully repaid, whereas “settled” indicates that the lender accepted less than the complete amount payable. Future lenders generally view a clean closed account more favourably.