Insider trading is one of the major concerns in securities markets because it can give certain individuals an unfair advantage over ordinary investors. When someone trades shares using confidential, price-sensitive information that has not been made public, other market participants may be placed at a disadvantage.
In India, the Securities and Exchange Board of India (SEBI) is responsible for regulating securities markets and investigating suspected insider trading. It uses trading data, company disclosures, investigations, and other evidence to identify possible violations. Depending on the findings and applicable law, SEBI can impose financial penalties, issue directions, and restrict individuals from participating in securities markets.
Understanding how SEBI detects and penalises insider trading helps investors, company employees, directors, and market professionals understand their legal responsibilities.
What Is Insider Trading Under Indian Law?
Insider trading generally involves dealing in securities while in possession of unpublished price-sensitive information (UPSI), in circumstances prohibited by securities law. UPSI is information relating to a company or its securities that is not generally available and, if published, is likely to materially affect the price of the securities.
Examples may include confidential information about financial results, dividends, mergers, acquisitions, major business developments, or changes in capital structure.
SEBI’s principal framework is the SEBI (Prohibition of Insider Trading) Regulations, 2015, read with relevant provisions of the SEBI Act, 1992. The regulations restrict trading while in possession of UPSI and prohibit unauthorised communication or procurement of such information, subject to applicable legal provisions and exceptions.
The framework also requires listed companies and other covered entities to maintain internal controls to prevent misuse of confidential information. The current regulatory text and amendments can be checked on SEBI’s official website.
How SEBI Detects Suspicious Trading Activity
Monitoring Unusual Trading Patterns
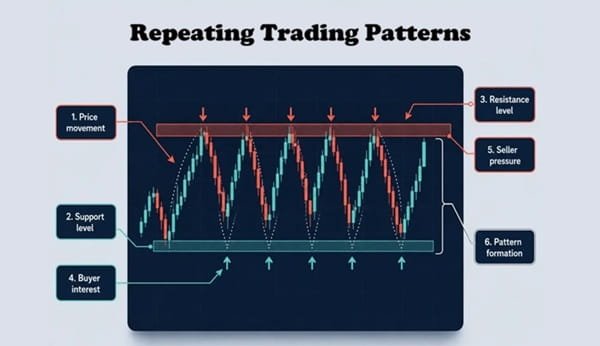
SEBI can examine trading activity for patterns that appear unusual in light of market conditions or public information. For example, a person may build a substantial position shortly before a company announces a major acquisition or unexpectedly strong financial results.
Such timing can raise questions about whether the trader had access to confidential information. However, unusual or profitable trading alone does not establish insider trading. Investigators must assess the circumstances and supporting evidence.
Analysing Trading and Demat Records
Trading records can help investigators establish when transactions occurred, how much was traded, and whether an account’s activity changed before an important announcement.
Relevant evidence may include order and transaction data, demat account records, beneficial ownership information, and links between accounts. These records can help establish the timing and scale of trading and identify relationships that require further examination.
SEBI may also examine whether transactions were conducted through accounts associated with relatives, business associates, or other connected persons. A relationship by itself does not prove wrongdoing; the surrounding evidence remains important.
Examining Access to Unpublished Information
Investigators may reconstruct how confidential information moved within a company or between people. They can examine who had access to relevant documents, who participated in meetings, and whether information was shared before a public announcement.
Evidence may include company records, communications, emails, access logs, and statements obtained through lawful investigative processes. This can help investigators assess whether a person possessed UPSI during the relevant trading period.
Comparing Trading With Company Announcements
The timing of trades is an important part of an insider trading investigation. SEBI may compare transaction dates with the period during which information remained unpublished and with the date on which it became publicly available.
For instance, if a person repeatedly trades shortly before significant announcements, the pattern may warrant closer scrutiny. Investigators must still examine the nature of the information, the person’s access to it, the trades involved, and any relevant explanations or legal exceptions.
How SEBI Conducts an Insider Trading Investigation
When suspicious activity is identified, SEBI may initiate an investigation and seek relevant information from companies, market intermediaries, and other persons, using its statutory powers.
The investigation may involve collecting trading records, examining communication trails, identifying persons with access to UPSI, and assessing whether trading occurred while the information remained unpublished. Investigators may also examine whether profits or avoided losses were linked to the suspected conduct.
SEBI can issue notices and seek explanations from persons under investigation. The findings are assessed against the applicable legal requirements and available evidence. A suspicious transaction is not, by itself, a final finding of guilt.
What Penalties Can SEBI Impose?
Section 15G of the SEBI Act, 1992 provides for monetary penalties for specified insider trading violations. The statutory penalty is not less than ₹10 lakh and may extend to ₹25 crore or three times the profits made from insider trading, whichever is higher. The applicable amount depends on the facts, the legal findings, and relevant statutory considerations.
In addition to monetary penalties, SEBI may use its powers under the SEBI Act to issue directions where legally justified. Depending on the case, these may include restraining a person from accessing or dealing in securities markets, directing disgorgement of unlawful gains, or imposing other appropriate measures.
The consequences depend on the violation established and the powers available under the relevant provisions. Criminal proceedings may also arise under applicable law in appropriate cases.
The Importance of Evidence and Due Process
SEBI must assess the evidence supporting an alleged violation. Trading before a major announcement, earning an unusual profit, or being related to a company employee does not automatically establish insider trading.
In Balram Garg v. SEBI (2022), the Supreme Court emphasised that suspicion and family relationships alone are insufficient to establish the necessary elements of an insider trading charge. The case illustrates why the evidence connecting a person to UPSI and the alleged trading conduct matters.
Persons facing allegations have an opportunity to respond through the applicable proceedings. Depending on the type of order, they may also have statutory rights of appeal.
How Companies and Investors Can Help Prevent Insider Trading
Companies can reduce the risk of insider trading by restricting access to confidential information, maintaining required records, monitoring designated persons’ trades, and enforcing internal codes of conduct.
Employees and directors should avoid trading while in possession of UPSI and should not share confidential price-sensitive information except where legally permitted. Investors should be cautious about trading tips that appear to rely on confidential corporate information.
SEBI’s framework also includes an informant mechanism intended to encourage reporting of suspected insider trading, subject to the applicable requirements.
Conclusion
SEBI detects suspected insider trading by analysing trading patterns, transaction records, company announcements, and evidence about access to confidential information. Investigations may lead to substantial monetary penalties, market restrictions, disgorgement, or other legal consequences where violations are established.
However, unusual trading is not proof of wrongdoing. A proper investigation must assess the evidence and apply the relevant legal standards. Understanding these rules helps market participants protect confidential information and supports fairer, more transparent securities markets.
Frequently Asked Questions
Q. How does SEBI detect insider trading?
SEBI may analyse unusual trading activity, transaction records, demat accounts, company disclosures, and evidence showing who had access to unpublished price-sensitive information.
Q. What is the maximum penalty for insider trading in India?
Under Section 15G of the SEBI Act, the penalty may extend to ₹25 crore or three times the profits made from insider trading, whichever is higher. The provision also specifies a minimum penalty of ₹10 lakh.
Q. Can SEBI investigate trades made through a relative’s account?
Yes, where the circumstances justify investigation. However, a family relationship alone does not prove insider trading; the relevant evidence must be assessed.
Q. Is trading before a company announcement always illegal?
No. Trading before an announcement is not automatically illegal. The legal assessment depends on whether prohibited trading occurred while in possession of UPSI and on the applicable rules and exceptions.
Q. Can SEBI stop someone from trading?
SEBI can issue market-access restrictions and other directions where authorised by law and justified by the circumstances of the case.
Q. What should someone do if SEBI issues an insider trading notice?
They should read the notice carefully, preserve relevant records, meet applicable deadlines, and consider obtaining advice from a lawyer experienced in securities regulation. The appropriate response depends on the allegations and evidence.